Aurum EX-AI 35% Early Withdrawal Rule: How the 12-Month Clock Works
One of the most important things to understand before using the Aurum EX-AI Bot is what happens when you withdraw funds before they have been active for 12 months.
The rule is straightforward, but its effect can be misunderstood:
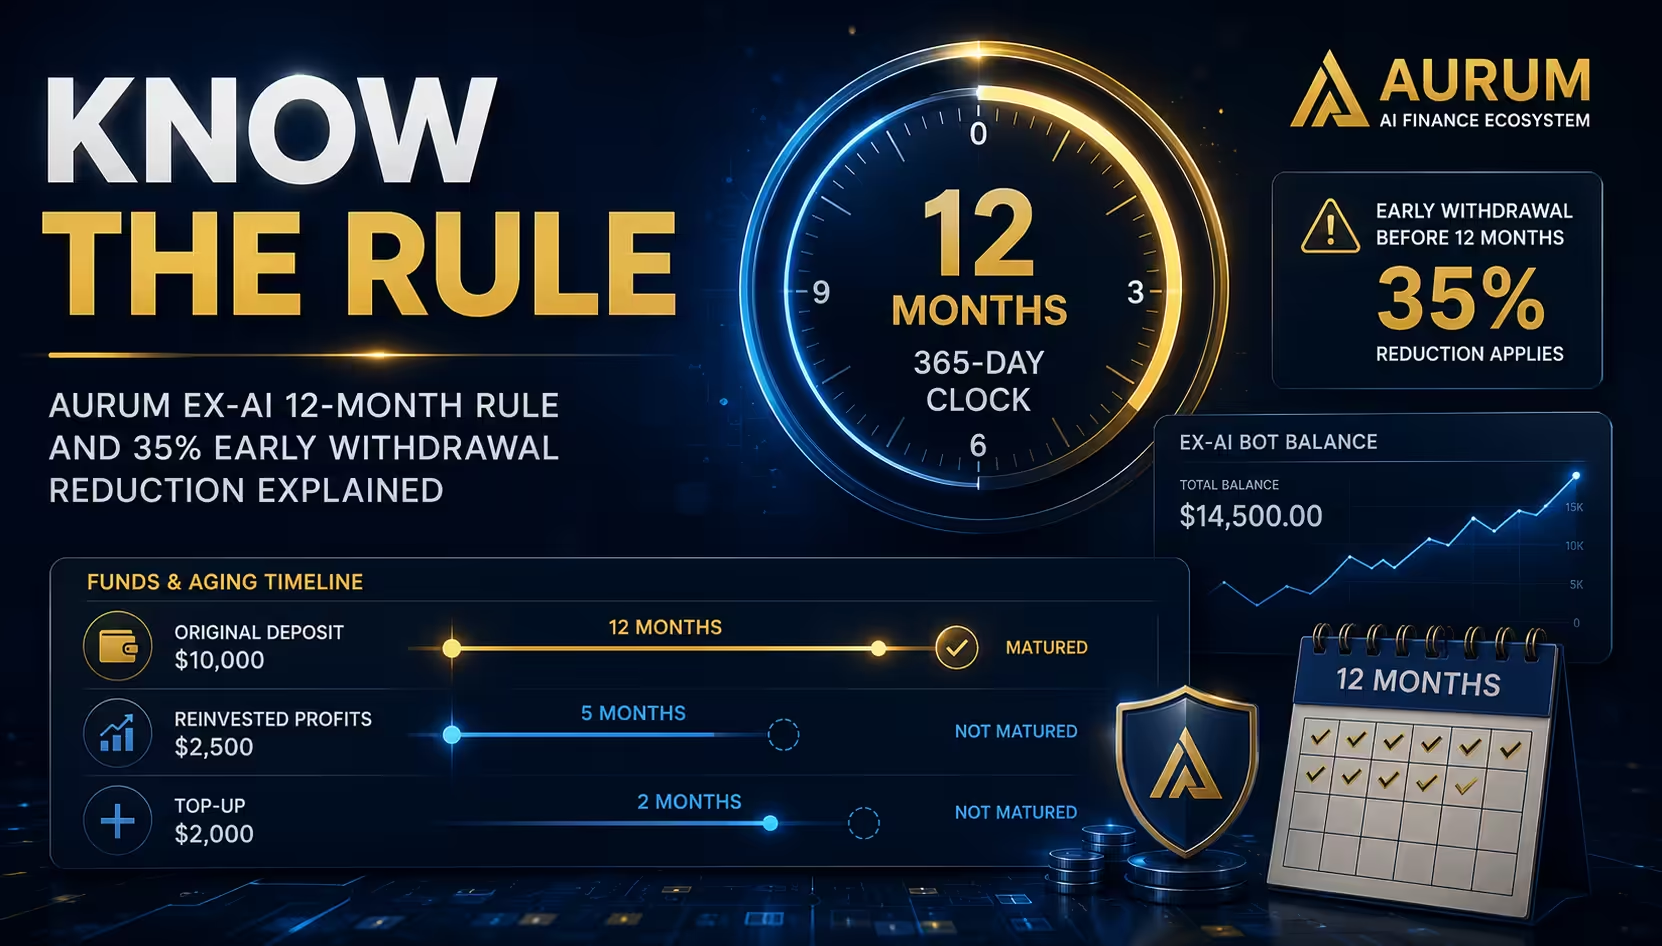
Funds inside an EX-AI Bot balance that are less than 12 months old are subject to a 35% early-withdrawal reduction.
That can include more than the original deposit.
Depending on how your account is structured, the rule can also apply to newer top-ups, accumulated profits, and amounts added to the bot through reinvestment.
This means someone could see that their bot balance has grown, request an early withdrawal, and receive substantially less than the balance shown on the screen.
The purpose of this article is to explain the rule clearly, show the math without relying on projected trading returns, and help members think about liquidity before activating reinvestment.
Important: This article is for education and general information only. Aurum involves digital assets and automated trading tools that carry risk. Results are not guaranteed, and losses are possible. Always review the current terms displayed inside your account.
The Quick Answer
If you withdraw an amount from your EX-AI Bot balance before that amount has completed its 12-month period, a 35% reduction applies to the amount being withdrawn.
For example:
- Requested withdrawal: $5,000
- 35% reduction: $1,750
- Remaining withdrawal amount: $3,250
The basic calculation is:
Withdrawal amount × 35% = early-withdrawal reduction
Then:
Withdrawal amount − reduction = amount remaining before any other applicable fees
This is not a trading-performance calculation.
It simply demonstrates how the 35% rule affects an early withdrawal.
What Does “Less Than 12 Months Old” Mean?
The 12-month period is best understood as a separate aging clock for money placed into the bot.
The original deposit begins its own 365-day period when it is activated.
However, adding more money later does not make that new money inherit the age of the original deposit.
Each new amount begins its own 365-day period.
That can include:
- The original EX-AI deposit
- A later one-time top-up
- Money added through reinvestment
- Accumulated daily profits retained inside the bot
- Additional deposits created at different times
This distinction matters because a single bot balance may contain funds with several different ages.
Part of the balance may have completed 12 months, while another part may still be within its first year.
The Original Deposit Has Its Own Clock
Assume someone creates an EX-AI deposit of $10,000 on January 1.
That $10,000 begins its own 12-month period on that date.
If no additional money is added to the bot, the original amount would reach its one-year point around the following January, subject to the platform’s exact counting rules and current terms.
The important point is that the clock belongs to that deposit.
It is not reset simply because the account later earns profits.
However, any new amounts added through reinvestment begin separate clocks of their own.
Reinvested Profits Have New 365-Day Clocks
This is where the rule becomes especially important.
Suppose the original deposit has been active for six months.
During that period, the member keeps the reinvestment option turned on, causing profits to be added back into the bot balance.
The original deposit may now be six months old.
But a profit amount reinvested yesterday is only one day old.
A profit amount reinvested two months ago is approximately two months old.
Each added amount is therefore at a different point in its own 365-day period.
This means that reaching the first anniversary of the original deposit does not automatically mean that everything displayed in the bot balance is more than 12 months old.
Newer reinvested amounts remain subject to the 35% early-withdrawal rule until their individual aging periods are complete.
Reinvestment Does Not Make Every Dollar the Same Age
It is easy to look at one bot-balance number and think of it as a single deposit.
Operationally, it is more useful to think of the balance as several layers:
- The original principal
- Profits added during the first month
- Profits added during the second month
- Later profits
- Manual top-ups
- Any additional amount placed into the bot
Each layer can have a different start date.
That is why members should not assume that the entire balance becomes eligible for withdrawal without the 35% reduction on the anniversary of the first deposit.
The age of each amount matters.
What Does the 35% Rule Apply To?
The rule applies to funds being withdrawn from the EX-AI Bot balance while those funds are less than 12 months old.
That can include:
Original principal
If the original deposit has not completed its 12-month period, withdrawing it early triggers the reduction.
Accumulated bot profits
When profits remain inside the bot balance, they are also subject to the rule based on when they were added.
Reinvested amounts
A reinvested amount begins a new aging period rather than receiving the date of the original deposit.
Later top-ups
Adding more funds several months after the first deposit creates a separate 365-day period for that additional amount.
The key concept is that the rule is not limited only to the original principal.
It applies to the amount in the bot balance that has not yet completed its required time.
Full Withdrawal Example
Assume a member has the following EX-AI Bot balance:
- Original deposit: $10,000
- Accumulated profits: $4,500
- Total bot balance: $14,500
For this example, assume the entire $14,500 is less than 12 months old and the member requests a full withdrawal.
The calculation would be:
$14,500 × 35% = $5,075
The remaining amount would be:
$14,500 − $5,075 = $9,425
Even though the displayed balance is $14,500, the amount remaining after the 35% reduction would be $9,425 before considering any other applicable transaction or platform fees.
This illustrates an important point:
A positive bot balance does not necessarily mean a member will receive the full displayed amount when withdrawing early.
In this example, the early-withdrawal reduction is large enough that the amount received is below the original $10,000 deposit.
Partial Withdrawal Example
The same percentage applies when someone withdraws only part of the balance.
Assume the bot balance is $14,500, but the member requests only $5,000.
The calculation would be:
$5,000 × 35% = $1,750
The remaining withdrawal amount would be:
$5,000 − $1,750 = $3,250
The unrequested portion would remain inside the bot, subject to the platform’s current rules and the individual aging periods of the funds.
A partial withdrawal does not make the percentage smaller.
It simply applies the percentage to a smaller requested amount.
What Happens When Some Funds Are Older Than 12 Months?
This is one of the most important questions for a member with multiple deposits, top-ups, or reinvested amounts.
Consider this simplified example:
- Original deposit: $10,000, now more than 12 months old
- Recent reinvested profits: $2,000, less than 12 months old
- Total balance: $12,000
The original $10,000 and the newer $2,000 do not have the same withdrawal status.
The newer portion remains subject to the 35% rule.
The exact result can depend on how Aurum identifies which funds are being withdrawn first.
For example, a platform may apply a withdrawal against older funds first, newer funds first, or according to another internal accounting method.
Do not assume.
Before withdrawing from a mixed-age balance, confirm inside your dashboard or with official support:
- Which amount is considered eligible
- Which portion is still under 12 months
- How the withdrawal amount will be allocated
- The reduction shown before confirming
- Whether any other fees apply
Review the final calculation before authorizing the transaction.
Reinvestment On Versus Reinvestment Off
The reinvestment setting can significantly affect how much money continues accumulating inside the bot.
Reinvestment turned on
When reinvestment is active, daily profits are added back into the bot balance.
This can increase the amount participating in the strategy.
It also creates new amounts with newer 365-day clocks.
The potential benefit is continued compounding.
The tradeoff is that more of the growing bot balance may consist of funds that have not completed their individual 12-month periods.
Reinvestment turned off
When reinvestment is turned off, profits may be directed to the member’s Main balance rather than continuously added to the EX-AI Bot balance.
The 35% early-withdrawal reduction applies to qualifying funds inside the bot balance.
Profits sent to Main are not continually being added back into that bot balance.
Members should still check whether the Main balance has any separate withdrawal procedures, processing windows, or fees.
The practical difference is:
- Reinvestment on: profits continue building inside the bot
- Reinvestment off: profits are separated from the active bot balance
Neither choice is automatically right for everyone.
The decision depends on a person’s goals, liquidity needs, risk tolerance, and understanding of the platform.
Why Liquidity Planning Matters
Before creating an EX-AI deposit, ask yourself:
Could I reasonably leave this money untouched for at least 12 months?
If the answer is no, consider whether the amount being deposited is too high.
Unexpected expenses happen.
People lose jobs, face medical bills, need vehicle repairs, or encounter family emergencies.
If money may be needed for essential expenses, it should not be placed into a high-risk strategy with a substantial early-withdrawal reduction.
A 35% reduction is significant.
It should be treated as a real cost when planning how much money to place into the bot.
Never deposit:
- Emergency savings
- Rent or mortgage money
- Tax money
- Money needed for debt payments
- Money reserved for medical expenses
- Funds required for ordinary living costs
- Borrowed money you cannot comfortably repay
Automation does not remove financial risk.
The Two-Deposit Approach
Some members may choose to divide their funds between separate EX-AI deposits rather than placing everything into one deposit with one reinvestment setting.
For example:
Deposit A: Reinvestment off
Profits are directed away from the bot balance and into Main, subject to the current platform rules.
This may appeal to someone who wants greater access to ongoing profits rather than continually adding them back into the bot.
Deposit B: Reinvestment on
Profits remain inside the bot and continue being reinvested.
This may appeal to someone focused on longer-term compounding who understands that newer reinvested amounts begin their own 365-day periods.
This type of structure can make it easier to separate two different goals.
However, it does not remove risk, guarantee profitability, or eliminate the 35% rule.
Every deposit and added amount should be reviewed according to its own start date and current platform terms.
Common Misunderstandings
“Only my original deposit is subject to the rule.”
Not necessarily.
Newer top-ups, accumulated bot profits, and reinvested amounts are also subject to the rule while they are less than 12 months old.
“After my original deposit reaches one year, the whole balance is eligible.”
Not necessarily.
Amounts added later have separate 365-day periods.
“Reinvesting profits gives them the same date as the first deposit.”
No.
Newly added amounts begin separate clocks.
“The 35% reduction applies only to profits.”
No.
It applies to the qualifying amount being withdrawn, including principal and profits that are less than 12 months old.
“If the bot has earned money, I cannot receive less than my original deposit.”
That is incorrect.
A large early-withdrawal reduction can cause the net amount received to be below the original deposit, even when the displayed bot balance is higher.
“A partial withdrawal avoids the 35% rule.”
No.
The rule still applies to the amount withdrawn.
Questions to Ask Before Creating a Deposit
Before moving money into EX-AI, make sure you can answer these questions:
- Do I understand the 35% early-withdrawal rule?
- Can I leave this money in place for at least 12 months?
- Do I understand that reinvested amounts have separate clocks?
- Do I know whether reinvestment is currently on or off?
- Do I understand the difference between the bot balance and Main balance?
- Have I reviewed the latest withdrawal terms inside my account?
- Am I using only money I can afford to risk?
- Do I understand that trading results are not guaranteed?
- Do I know how to obtain help before confirming a withdrawal?
- Have I enabled two-factor authentication and secured my account?
Understanding the rules before depositing is much easier than discovering them during an emergency.
Frequently Asked Questions
Does Aurum prevent me from withdrawing before 12 months?
The rule does not mean that early withdrawal is impossible.
It means that eligible funds in the EX-AI Bot balance that are less than 12 months old are reduced by 35% when withdrawn.
Withdrawal availability can also depend on the platform’s current processing windows and account rules.
Is the 35% applied only to profit?
No.
It applies to the qualifying withdrawal amount, including principal, profits, top-ups, or reinvested amounts that are less than 12 months old.
Does the original deposit’s anniversary release all reinvested profits?
No.
Amounts added later have their own 365-day periods.
Does reinvestment reset the clock on my original principal?
No.
The original deposit retains its own start date, while newly reinvested amounts begin separate periods.
Can I turn reinvestment off?
The EX-AI account interface may allow members to change the reinvestment setting while a deposit remains active. Review the current controls and terms inside your account before making changes.
Are profits sent to Main subject to the same 35% bot rule?
The rule described here applies to qualifying funds inside the EX-AI Bot balance.
Profits directed to Main are treated separately from amounts continually reinvested into the bot. Confirm any separate Main-balance withdrawal terms before acting.
Are returns guaranteed if I leave the funds for 12 months?
No.
The 12-month rule relates to the early-withdrawal reduction. It does not guarantee trading performance, profits, or the return of principal.
Understand the Rule Before You Reinvest
The Aurum EX-AI Bot may look simple from the dashboard, but the age of the money inside the balance matters.
The most important points are:
- Funds withdrawn before completing 12 months are reduced by 35%.
- The rule applies to principal and profits.
- New top-ups and reinvested amounts begin separate 365-day periods.
- The first deposit’s anniversary may not make the entire bot balance mature.
- Reinvestment can increase the amount inside the bot while also creating newer fund layers.
- An early withdrawal can leave someone with less than the original amount deposited.
- Money needed for emergencies or essential expenses should not be placed at risk.
Before depositing or changing your reinvestment setting, review the terms carefully and make sure the structure fits your liquidity needs.
New to the platform? Start with our guide to choosing the Aurum EX-AI Bot as a beginner.
For personal help understanding the setup and withdrawal rules, schedule a guided Aurum onboarding call.
Risk Disclosure
This article is for education and general information only and is not financial, investment, legal, or tax advice. Aurum involves digital assets, automated trading, platform risk, technology risk, regulatory risk, liquidity risk, and the possibility of losing money. Trading results are not guaranteed. Past performance does not guarantee future results. Platform terms, fees, withdrawal windows, and eligibility requirements may change. Review the current information displayed inside your account and never use money you cannot afford to risk.